Cardoso: Why CBN took market by surprise on interest rate
By Babajide Komolafe, Economy Editor
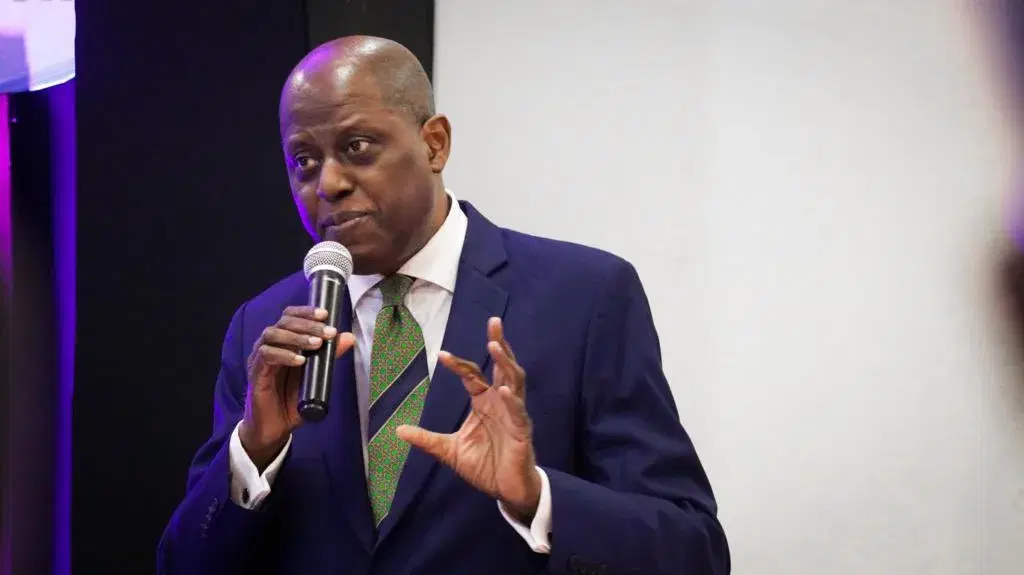
BANGKOK, THAILAND — The Governor of the Central Bank of Nigeria (CBN), Olayemi Cardoso, addressed the unexpected nature of the apex bank’s recent monetary policy decision, attributing it to the necessity of rectifying a flawed monetary policy transmission mechanism and enhancing macroeconomic conditions.
Speaking at a panel discussion titled “How Central Banks Decide” during the ongoing International Monetary Fund (IMF) and World Bank Annual Meetings, Cardoso noted that Nigeria’s external reserves have reached their highest levels in 18 years. He highlighted a consistent decline in inflation and steady economic growth, factors that created the opportunity for the CBN to rectify existing imbalances.
Responding to a question posed by Dan Katz, First Deputy Managing Director of the IMF, regarding the CBN’s communication strategy surrounding the surprising decision, Cardoso emphasized that the outcome stemmed from intentional communication and prior reforms.
“You are absolutely right. It took the market by surprise, and markets, as we know, generally don’t like surprises,” Cardoso acknowledged.
He pointed to several developments that enhanced the policy framework leading up to the Monetary Policy Committee (MPC) meeting, notably improved coordination between fiscal and monetary authorities.
“We signed a memorandum of understanding between fiscal and monetary authorities to ensure alignment, which was very positively received,” he stated.
Cardoso also mentioned the introduction of an overnight financing rate, which he said provided clearer insights into prevailing interest rate conditions compared to the previous system.
“In terms of macroeconomic conditions, Nigeria is in a strong position. Our external reserves are the highest they have been in 18 years,” Cardoso said. He further noted that inflation is on a downward trajectory and economic growth is maintaining a reasonable pace, creating the space for adjustments in the monetary policy transmission process.
Nigeria’s Unique Inflation Cycle
Cardoso explained that Nigeria’s monetary policy decisions must be tailored to the country’s unique economic context rather than simply mimicking actions taken by other central banks. He pointed out that Nigeria’s inflation experience differs significantly from that of many other countries due to major domestic policy changes, such as foreign exchange harmonization and the removal of petrol subsidies, which occurred at different points in the global inflation cycle.
“Our inflation cycle differs noticeably from that of much of the world because we implemented significant changes like foreign exchange harmonization and subsidy removal at a distinct time in the global inflation trends,” he stated.
This divergence necessitates that the MPC evaluates Nigeria’s economic circumstances independently of decisions made in advanced economies, Cardoso asserted. He acknowledged that while MPC members monitor global trends, including actions by the United States, the CBN must remain focused on domestic economic realities.
MPC Decision-Making Process
In discussing the MPC’s decision-making process, Cardoso underscored the importance of member independence to foster thorough deliberations and avoid groupthink. The MPC consists of 12 members—seven from within the bank and five external members—who bring diverse perspectives that enhance debate and challenge existing assumptions.
Cardoso explained that the CBN intentionally recruited independent-minded external members as part of its transition from currency crisis to economic stabilization to bolster the credibility of its monetary policy decisions.
“Overall, they provide a distinct perspective compared to internal members,” Cardoso noted. Internal members, he added, are encouraged to arrive at their conclusions independently before formal MPC meetings, allowing for a comprehensive review of relevant data.
“I don’t hold meetings with internal members to pre-determine conclusions before we gather for the MPC meeting,” he stated. Effective chairmanship, he noted, involves identifying common ground before addressing disagreements to avoid getting sidetracked by minor issues.
Communication Strategy and Credibility
Cardoso emphasized the significance of the CBN’s communication strategy in helping market participants grasp the rationale behind the unexpected decision. He indicated that he engaged with journalists in greater depth than usual following the MPC meeting to elucidate the economic challenges and reforms that led to the decision.
“Rather than merely announcing the policy action, it was essential to articulate the context of the economic landscape,” he said. He added that market participants were already aware of the inefficiencies in the monetary policy transmission process from their experiences in financial markets.
“The market understood this because they operate within it and realized the logic behind our actions,” Cardoso stated, reinforcing that the successful management of unexpected decisions is reliant on the credibility the CBN has cultivated over time.
“To navigate such situations effectively, one must build credibility with the market, ensuring that participants have consistently observed our commitment to sound practices over time,” he concluded.